How to Pay for Home Care in Orange County & the Inland Empire: Private Pay and Long-Term Care Insurance
A clear, unhurried look at how families fund private in-home care, from private pay to long-term care insurance, and how to build a plan that lasts.
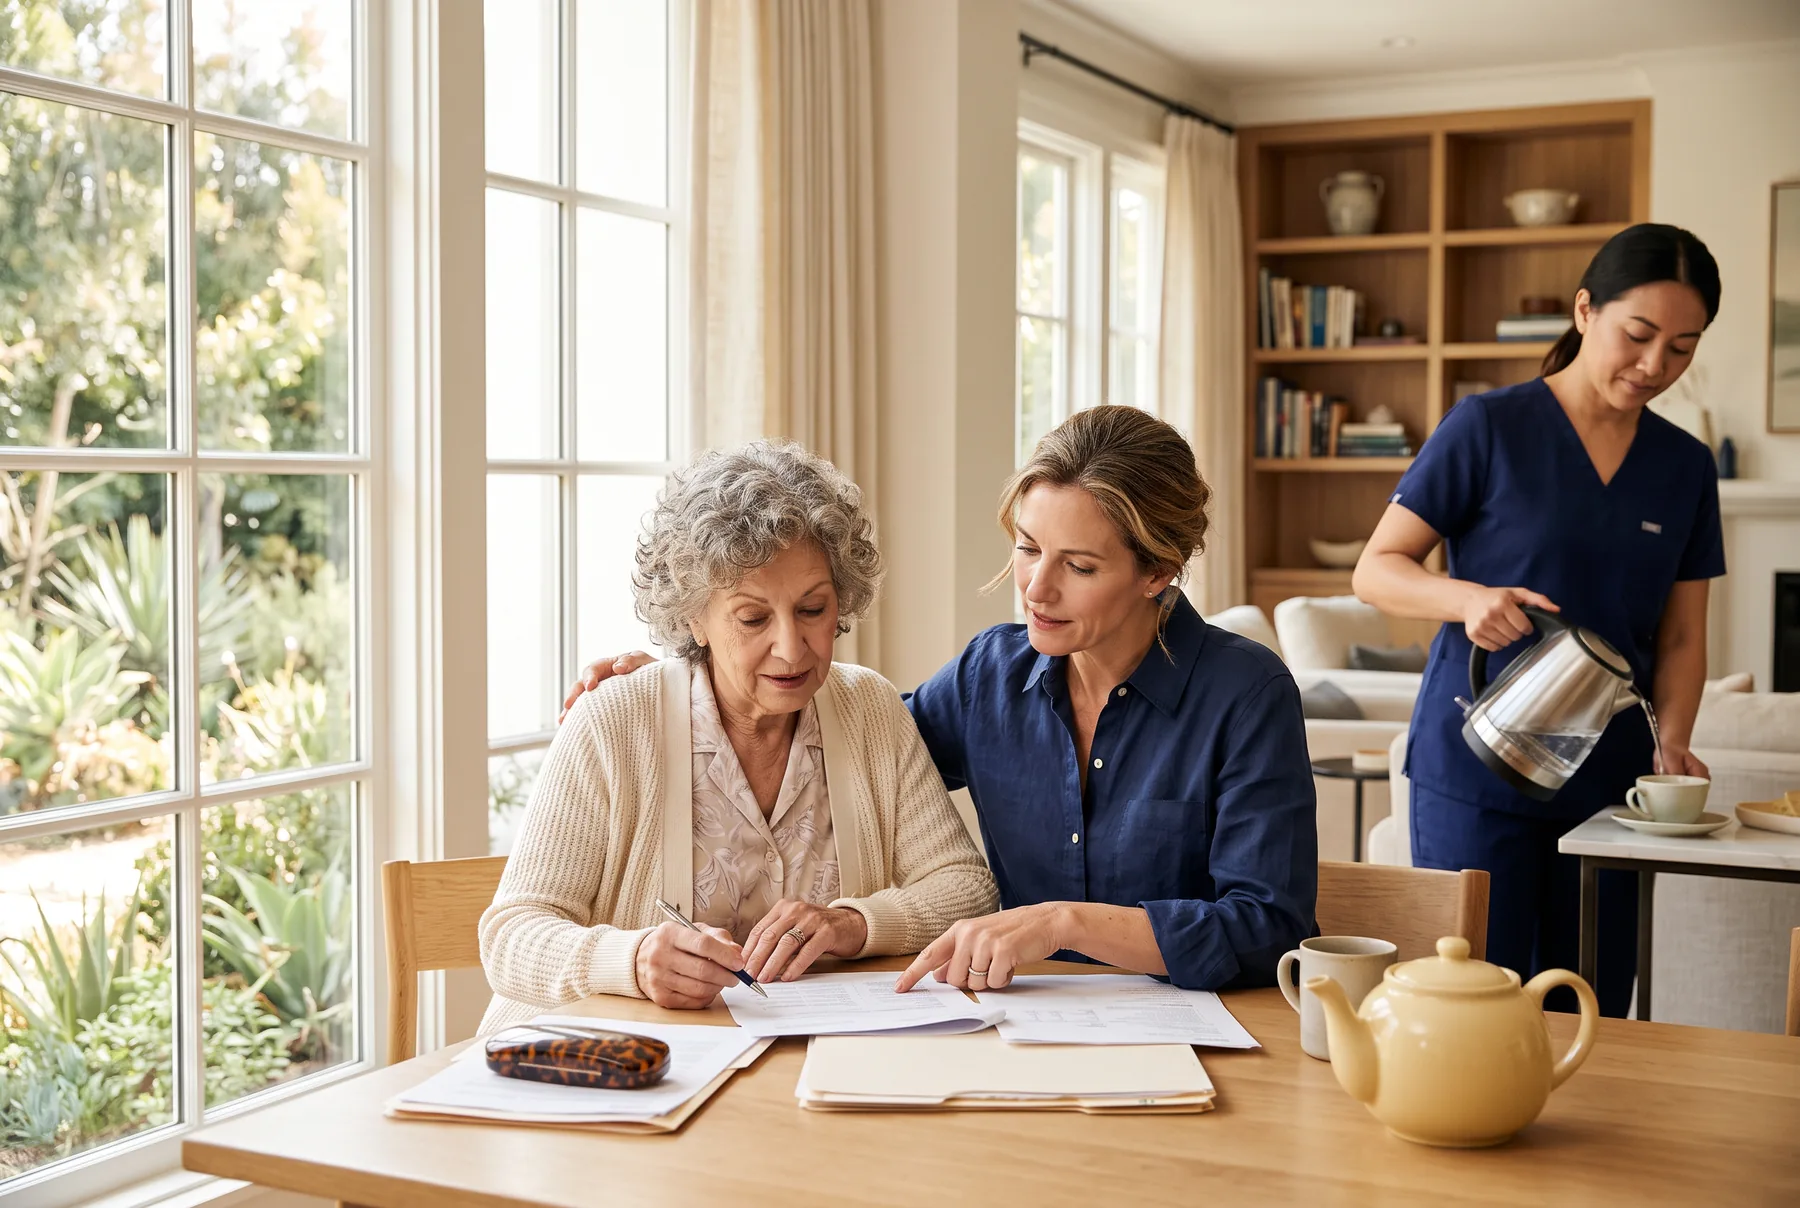
For most families, the conversation about home care starts with a question nobody wants to ask out loud: what is this going to cost, and who pays for it? It deserves a straight answer. Yet families across Orange County and the Inland Empire tell us the same thing — they spend weeks calling agencies, insurers and county offices and still cannot get a clear picture.
This guide lays out the main ways local families actually pay for in-home care, what each one covers, what it does not, and how they can be combined — so you can walk into the decision knowing what your options really are.
First, Know What You Are Buying
Before comparing payment sources, it helps to be precise about the service, because the words get used loosely and that confusion costs families money.
- In-home care (non-medical / personal care): Help with bathing, dressing, grooming, toileting, transfers, mobility, meals, medication reminders, light housekeeping and companionship. This is what most families mean when they say “home care,” and it is what personal care services covers.
- Home health (skilled medical): Short-term, physician-ordered skilled nursing or therapy delivered at home — wound care, IV therapy, physical therapy after surgery. This is a different service with a different payment structure.
That distinction matters more than almost anything else in this guide, because every payment option below is about ongoing, non-medical care at home. Here is how families in Orange County and the Inland Empire typically cover it.
Option 1: Private Pay
Private pay simply means the family pays the agency directly, usually billed hourly. It is how the majority of in-home care in Orange County and the Inland Empire is funded, and it has real advantages: no eligibility process, no waiting period, no approval to obtain, and complete freedom over the schedule and the scope of care. You can start next week, adjust hours as needs change, and stop when you want.
Families commonly fund it from Social Security income, a pension, retirement savings, rental income, or a home sale — and adult children frequently split the cost among siblings.
A practical note: many families overestimate what they need at the start. Care does not have to be around the clock to be transformative. A few well-placed hours — mornings for bathing and breakfast, or afternoons through the risky sundown window — often deliver most of the safety benefit at a fraction of the cost. Start focused and expand as needed.
Option 2: Long-Term Care Insurance
If your loved one purchased a long-term care insurance policy years ago, that policy may be the single most valuable asset in this conversation — and it is astonishing how often families forget it exists or assume it only pays for nursing homes. Most modern LTC policies explicitly cover in-home care, and many were purchased precisely so the policyholder could avoid a facility.
Here is what to look for when you find the policy:
- Benefit trigger: Most policies pay once the person needs help with a set number of Activities of Daily Living (commonly two of six: bathing, dressing, eating, toileting, transferring, continence) or has a documented cognitive impairment.
- Elimination period: A waiting period — often 30, 60 or 90 days — during which you pay out of pocket before benefits begin. Some policies count calendar days, others count days of paid service. Confirm which, in writing.
- Daily or monthly benefit amount: The cap on what the policy pays per day or month.
- Provider requirements: Many policies require care from a licensed agency rather than an independently hired caregiver. Hiring privately to save money can inadvertently void the benefit.
Start the claim early. The paperwork, the assessment and the elimination period all take time, and beginning the process before care is urgent gives you room to plan.
Ready to use a policy? Our guide to using long-term care insurance for home care walks through the claim step by step, and we help families with the paperwork.
Some veterans’ families also explore VA programs alongside private pay and insurance; an accredited Veterans Service Officer can explain what may apply, and our guide to veteran home care covers how we support veterans at home.
Care does not have to be around the clock to be transformative.
Building a Plan That Actually Works
In practice, most sustainable care plans are not one funding source. They are a stack.
- Inventory what exists first. Before you price anything, find out whether there is a long-term care insurance policy. Families routinely discover a resource they had forgotten.
- Start the slow paperwork now. Insurance claims and elimination periods take time. Private pay can bridge the gap while they process.
- Target the hours where risk is highest. Mornings, evenings, bath days and medication times carry the most risk. Cover those first.
- Use respite care to protect the family caregiver. When the unpaid family caregiver burns out, the whole plan collapses and the cost of the alternative is far higher.
- Revisit every few months. Needs change. So should the plan.
Why Who You Hire Changes the Value of Every Dollar
When families compare hourly rates, they are usually comparing numbers that look similar and represent very different things. The credential of the person walking through the door is what separates them.
Premium Care In Home Care Services is a home care agency serving Orange County and the Inland Empire staffed 100% by Certified Nursing Assistants (CNAs). Every caregiver we send has completed state-approved clinical training and passed a competency exam — covering safe transfers and mobility assistance, recognizing early changes in a client’s condition, infection control, dietary restrictions, and accurate documentation. You can read more about what that standard means in practice.
That matters financially as well as clinically. A caregiver trained to transfer someone safely prevents the fall that leads to a hip fracture. One trained to notice that a wound looks different today, or that confusion is new, catches the problem while it is still small. Avoiding a single hospitalization can outweigh months of care costs — and it keeps your loved one home, which is the entire point.
As an agency, we also carry the payroll taxes, workers’ compensation, liability coverage, background screening, supervision and backup staffing that a privately hired caregiver does not. Families who hire independently to save a few dollars an hour often find they have quietly become an employer — and that many LTC policies will not reimburse the arrangement.
Start With a Conversation, Not a Contract
You do not need the funding figured out before you call. The most useful first step is usually to describe your situation to someone who has helped local families through the same maze, and find out what a realistic schedule and cost look like.
We serve families across Orange County and the Inland Empire; please call to confirm we serve your area. If you are weighing options for a parent, a spouse or yourself, request a complimentary consultation or call (909) 284-8657. There is no obligation and no pressure — just a clear conversation about what care would look like and how families like yours pay for it.
This article is general information about payment options and is not financial, legal or benefits advice. Eligibility rules for VA benefits and insurance policies change and vary by individual circumstance — confirm details with the relevant program, your insurer, or an accredited advisor.
Premium Care serves families across Orange County and the Inland Empire. Call (909) 284-8657 to arrange a complimentary consultation.